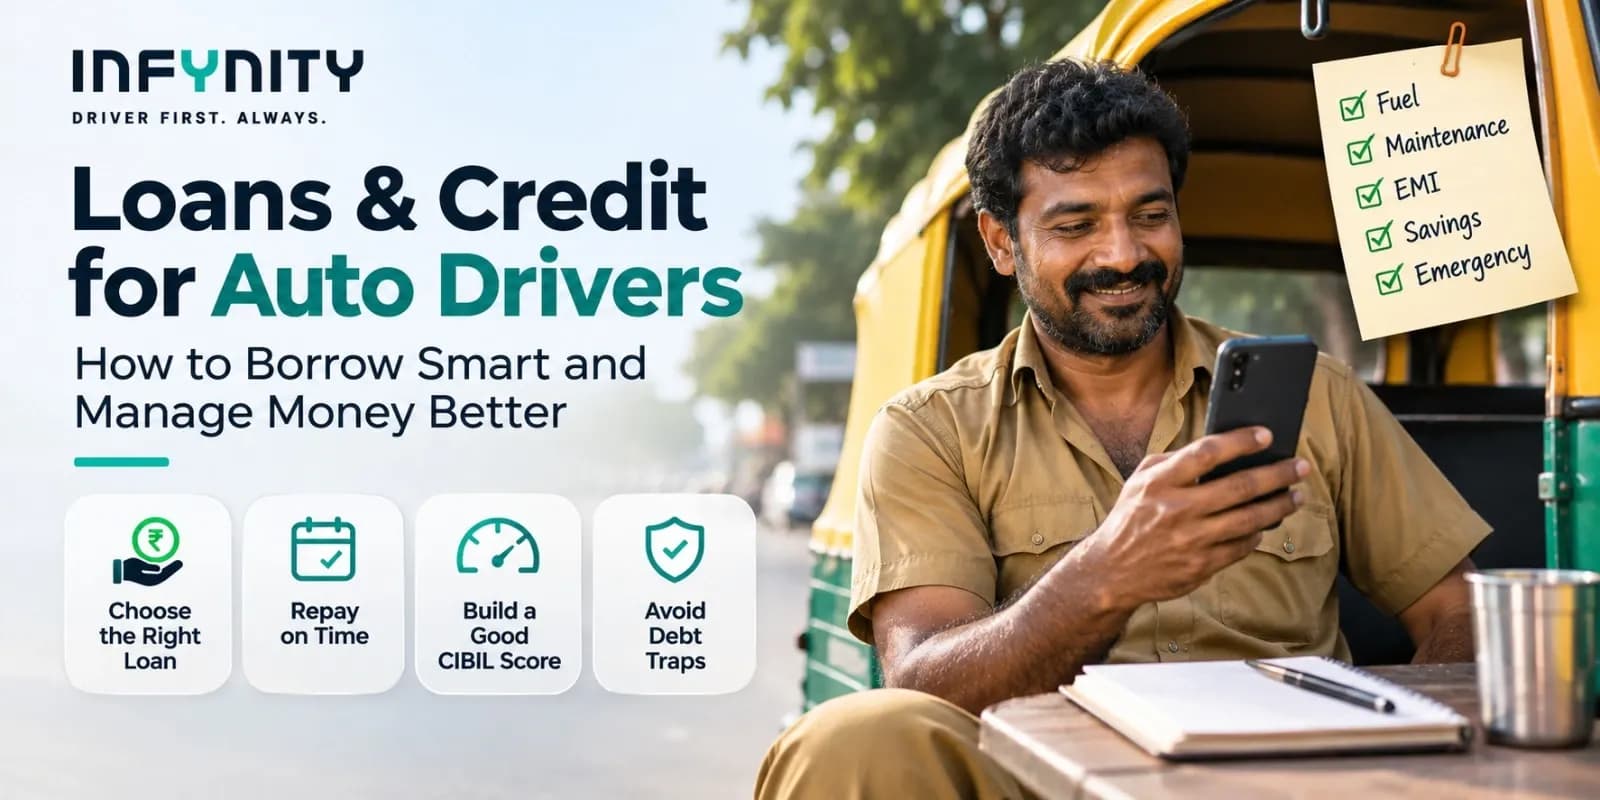
For many auto drivers, cab drivers and delivery partners, income can vary from one day to another. Some days bring good earnings, while others are unpredictable. And when an unexpected expense comes up — a vehicle repair, medical bill, household expense or urgent payment — having access to credit can make a difference.
Loans and credit facilities can provide financial support when you need it. But borrowing without understanding the costs, repayment terms and risks can create a debt cycle that becomes difficult to escape.
The key is not to avoid credit altogether. It is to understand how credit works, borrow only what you need and repay it responsibly.
What Is a Loan, and When Should You Consider One?
A loan is money borrowed from a bank, NBFC or other authorised lender that must be repaid over an agreed period, usually with interest and applicable charges.
Depending on your needs, you may come across different types of loans:
- Personal loans: Unsecured loans that can be used for eligible personal expenses.
- Emergency loans: Short-term borrowing options for unexpected financial requirements.
- Vehicle loans: Financing used to purchase a vehicle.
- Business or working-capital loans: Credit that can help manage business-related expenses.
- Secured loans: Loans backed by an asset or collateral, subject to the lender's terms.
For a driver, borrowing may make sense when it helps address an urgent need or supports the ability to earn. For example, repairing a vehicle that you depend on for daily income may be a more practical reason to borrow than taking a loan for an unnecessary purchase.
Before applying, ask yourself three questions:
- Is this expense genuinely necessary?
- Can I manage the repayment even if my income is lower next month?
- Have I compared the total cost of borrowing?
If you cannot confidently answer these questions, reconsider the loan.
Understand the Real Cost of a Loan Before Accepting It
One common mistake borrowers make is looking only at the EMI — the monthly instalment.
A small EMI may look affordable, but a longer repayment period or higher interest rate can make the loan considerably more expensive.
Before accepting any loan, check:
- Interest rate: The rate charged on the borrowed amount.
- Annual Percentage Rate (APR): An annualised measure of the overall cost of credit, including applicable charges.
- Processing fee: A charge that may be deducted or collected when the loan is processed.
- Loan tenure: The time you have to repay the loan.
- Late-payment charges: Additional charges that may apply when you miss a payment.
- Prepayment or foreclosure conditions: The terms and charges, if any, for repaying the loan early.
In India, regulated lenders are required to provide borrowers with a Key Facts Statement (KFS) for applicable loan products. It helps explain important loan details, including the APR and repayment information.
Remember: Never accept a loan simply because the EMI looks affordable. Understand how much you will repay in total.
How to Use Credit Cards Without Falling Into Debt
A credit card lets you make purchases using a credit limit provided by the issuing bank. It can be useful for planned expenses and convenient payments, but only when managed carefully.
Here are some practical credit card habits:
Pay the total outstanding amount
Whenever possible, pay the full amount due before the payment deadline. Paying only the minimum amount due can leave a balance that attracts interest and other applicable charges.
Keep your credit utilisation low
Credit utilisation refers to how much of your available credit limit you use. For example, if your credit limit is ₹50,000 and your outstanding balance is ₹10,000, your utilisation is 20%.
Using a smaller portion of your available limit is generally healthier for your credit profile than regularly maxing out your card.
Avoid cash withdrawals using your credit card
Cash advances can attract additional fees and interest. They are usually an expensive way to access money.
Do not treat your credit limit as extra income
A credit limit is borrowed money, not an increase in your earnings. Spend only what you can comfortably repay.
What Is a CIBIL Score, and Why Does It Matter?
Your CIBIL Score is a three-digit number ranging from 300 to 900 that summarises your credit history. Banks and financial institutions may consider it when evaluating your loan or credit application.
Your credit history can reflect:
- Whether you pay EMIs and credit card bills on time.
- How much of your available credit you use.
- How long you have maintained credit accounts.
- How frequently you apply for new credit.
- Your existing and previous credit accounts.
A stronger credit history can improve your chances of getting approved for credit, although lenders also consider income, existing obligations, eligibility and their own lending policies.
Simple ways to maintain a healthy credit score
- Pay loan EMIs and credit card bills on time.
- Avoid missing payment deadlines.
- Keep credit card balances under control.
- Avoid applying for several loans or cards within a short period.
- Check your credit report periodically for incorrect entries.
- Clear outstanding dues and follow up on any reporting errors.
One important point: A good credit score does not guarantee loan approval. Every lender has its own eligibility requirements.
Five Credit Mistakes You Should Avoid
Small financial decisions can have long-term consequences. Watch out for these common mistakes:
1. Borrowing from multiple lenders at once
Taking several loans to manage existing repayments can increase your financial burden. Understand your current obligations before applying for additional credit.
2. Missing EMI deadlines
Late payments can result in additional charges and negatively affect your credit history.
3. Taking a loan without reading the agreement
Always review the interest rate, APR, repayment schedule, charges and other conditions before accepting an offer.
4. Borrowing more than you need
A higher loan amount may mean a higher repayment burden. Borrow according to your actual requirement and repayment capacity.
5. Trusting unverified loan apps
Be careful with apps or agents promising guaranteed loans, instant approvals or unusually low interest rates. Verify the actual lender and check the terms before sharing personal information.
Never share your OTP, UPI PIN, passwords or banking credentials with anyone claiming to process a loan.
What Should Drivers Do When Income Is Unpredictable?
Unlike salaried employees, many drivers and gig workers earn different amounts on different days. This makes financial planning especially important.
A few habits can help:
- Plan repayments around realistic income: Do not calculate your repayment capacity using only your best earning days.
- Maintain an emergency reserve: Set aside a manageable amount whenever possible for unexpected expenses.
- Separate essential expenses: Account for fuel, vehicle maintenance, household costs and existing EMIs before deciding how much you can borrow.
- Track your repayments: Maintain a simple record of loan balances, EMI amounts and payment dates.
- Avoid borrowing to fund regular spending: If you repeatedly need loans for everyday expenses, review your budget and financial commitments.
Even small, consistent financial habits can help you manage uncertain income more effectively.
How Infynity Can Help Drivers Explore Financial Support
Drivers need more than a way to find their next ride. They also need access to useful services that support their everyday financial needs.
Infynity is designed around the needs of auto drivers, cab drivers, delivery partners and other gig workers. Through its financial support features, Infynity aims to help drivers explore available loan and emergency-money options when they need additional support.
Instead of making financial decisions in a hurry, take time to understand the available options, check eligibility and review the lender's repayment terms.
Before accepting any loan through an app or platform, always verify the name of the actual lending institution, the applicable interest rate, APR, charges and repayment conditions. Loan availability and approval depend on the lender's eligibility assessment.
The goal is simple: make informed financial decisions, manage credit responsibly and stay in control of your money.
Credit is a financial tool. Used responsibly, it can help you manage emergencies, handle important expenses and work towards your financial goals. Used carelessly, it can become a burden that affects your income and peace of mind.
Whether you are an auto driver, cab driver or delivery partner, understand the terms before borrowing, pay your dues on time and never take a loan you cannot reasonably repay.
Your earnings matter. Your financial future matters too.
Explore the services available on Infynity and take a more informed approach to managing your financial needs.
Disclaimer: This article is for general financial awareness and educational purposes only. It is not financial or investment advice. Infynity does not guarantee loan approval or credit eligibility. Loan products, availability, interest rates and repayment terms are determined by the respective lending institution. Always review the complete loan agreement before accepting credit.